Categories
Home Buying, Buyer Education, Buying & SellingPublished August 16, 2026
Could Portable Mortgages Change the Housing Market?
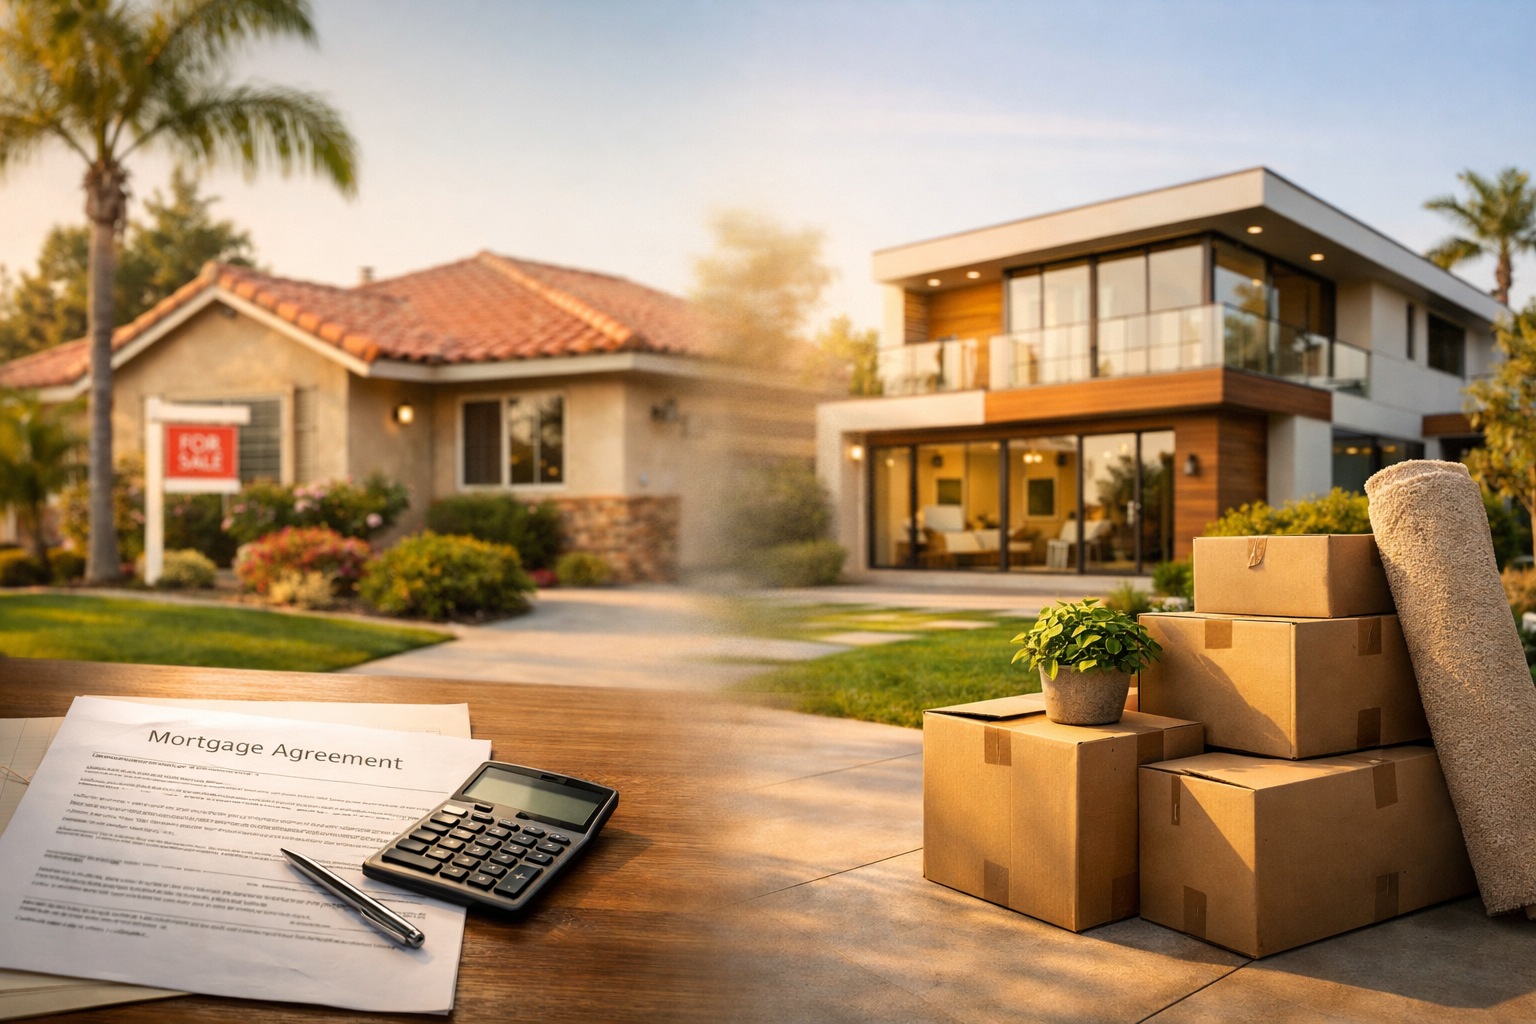
Housing policy can sound distant from everyday decisions, but discussions around portable mortgages could eventually influence how homeowners think about moving. A portable mortgage would allow a qualifying homeowner to transfer an existing mortgage, including its low interest rate, remaining balance, and loan term, from one home to another rather than paying it off and taking out an entirely new loan at current rates.
The concept is receiving growing attention because many homeowners hold mortgage rates far below today’s prevailing market rates. That gap has contributed to a widespread “lock-in effect,” where owners delay selling because giving up a low-rate loan could substantially increase their monthly housing costs.
Portable mortgages are not broadly available in the conventional U.S. mortgage market today. While federal housing regulators and policy analysts have evaluated portability and expanded loan-assumption models, there is currently no active, standardized Fannie Mae or Freddie Mac portable-mortgage program for everyday consumers.
Mortgage programs, eligibility requirements, and lending guidelines vary. Speak with a qualified mortgage professional about financing options available for your situation.
What Mortgage Portability Could Change
If a portable-mortgage framework were adopted on a broader scale, it could give qualifying homeowners more flexibility to move while retaining favorable financing terms. That could encourage homeowners who feel financially locked into their current properties to consider downsizing, relocating for work, or moving into a larger home.
Still, portability would not eliminate every financial factor involved in moving:
The Price Difference
A homeowner purchasing a higher-priced property would only transfer their existing mortgage balance. Any difference in price would still need to be covered through home-equity proceeds, cash down payments, or secondary financing.
Underwriting and Qualification
Borrowers would still need to meet lender guidelines, debt-to-income limits, credit requirements, and appraisal standards for the new property.
Transaction Costs
Standard closing costs, local transfer taxes, moving expenses, and other transaction-related costs would still apply.
The Risk of the “Wait and See” Approach
A common pitfall for both buyers and sellers during shifting markets is sitting on the sidelines to “watch what happens.”
When potential movers put their plans entirely on hold while waiting for a policy breakthrough or a major drop in interest rates, a familiar cycle can unfold:
Pent-Up Demand Builds
Sidelined buyers and sellers can accumulate while waiting for ideal market signals.
Competition Can Return Quickly
When rates adjust downward or new financing programs emerge, buyer demand may rebound rapidly.
Upward Pressure on Pricing
Increased buyer competition can lead to tighter inventory, fewer seller concessions, and upward pressure on home prices. Those changes can offset some of the monthly savings buyers hoped to gain by waiting.
Market timing is notoriously difficult. Homeowners and buyers who make moves based on their actual budget, lifestyle needs, and long-term equity goals are often in a stronger position than those trying to time national policy debates.
What Buyers Should Consider
Focus on Payment Comfort Over Headlines
A home that fits your monthly budget today can provide stability and an opportunity to build equity over time. If rates and qualifications allow in the future, financing may be revisited through refinancing. Future home prices and financing costs are uncertain, so it’s better to evaluate opportunities based on today’s numbers and your long-term plan.
Take Advantage of Negotiating Room
When fewer buyers are actively competing, you may have more leverage to negotiate price, request seller credits, or include inspection contingencies that can become harder to secure in a faster-moving market.
Dial In Your Pre-Approval
Working with a trusted local lender helps you understand your numbers and be ready to act when the right property appears.
What Sellers and Move-Up Buyers Should Consider
Evaluate Your Existing Equity
Some homeowners may have accumulated enough equity to reduce their next loan balance, contribute a larger down payment, or explore a rate buydown without waiting for special legislation. A personalized equity review can clarify what may be possible for your situation.
Understand Local Inventory Dynamics
If future policy shifts or rate changes bring more listings to the market, your property could face more direct competition than it does in a lower-inventory environment. Pricing, preparation, and marketing strategy will still matter.
Analyze Your Net Proceeds
A personalized equity review can show what your home could yield in today’s market and how those proceeds may translate into your next purchase.
Don’t Make a Move Based on Headlines Alone
Get a local strategy built around your budget, equity, timing, and the specific neighborhoods you’re considering.
What Will Still Matter Most
Policy discussions around portable mortgages highlight creative solutions to affordability, but national debates do not dictate day-to-day real estate values. Local employment, neighborhood supply, school districts, property condition, and community demand will continue to influence the market.
Evaluating your personal timeline and reviewing real neighborhood data will provide a clearer answer than waiting on speculative changes.
Your Next Move Starts With Local Numbers
National housing policy may shape future options, but your decision should be based on today’s inventory, pricing, financing choices, and personal goals in Southwest Riverside County.
Whether you’re considering a move within Southwest Riverside County, let’s build a clear plan around your next move.
>>> Explore Affordable Homes in Southwest Riverside County
>>> Let’s Get Your Blueprint for Buying or Selling Your Home
Call or text Richard “Rick” Rodriguez at (951) 498-4456
Follow on Instagram: @realtor_rick77
Brian Erhahon
| Brian & Mercedes Erhahon, RESWealthy Team | REAL | PLACE
or another way