Categories
Buyer Education, Home Buying, Mortgage & FinancePublished August 18, 2026
How Much Money Do I Actually Need to Buy a House?
How Much Money Do I Actually Need to Buy a House?
One of the first questions buyers ask me is:
“How much money do I actually need to buy?”
And usually what they really mean is:
“How much do I need in my bank account before I even start this process?”
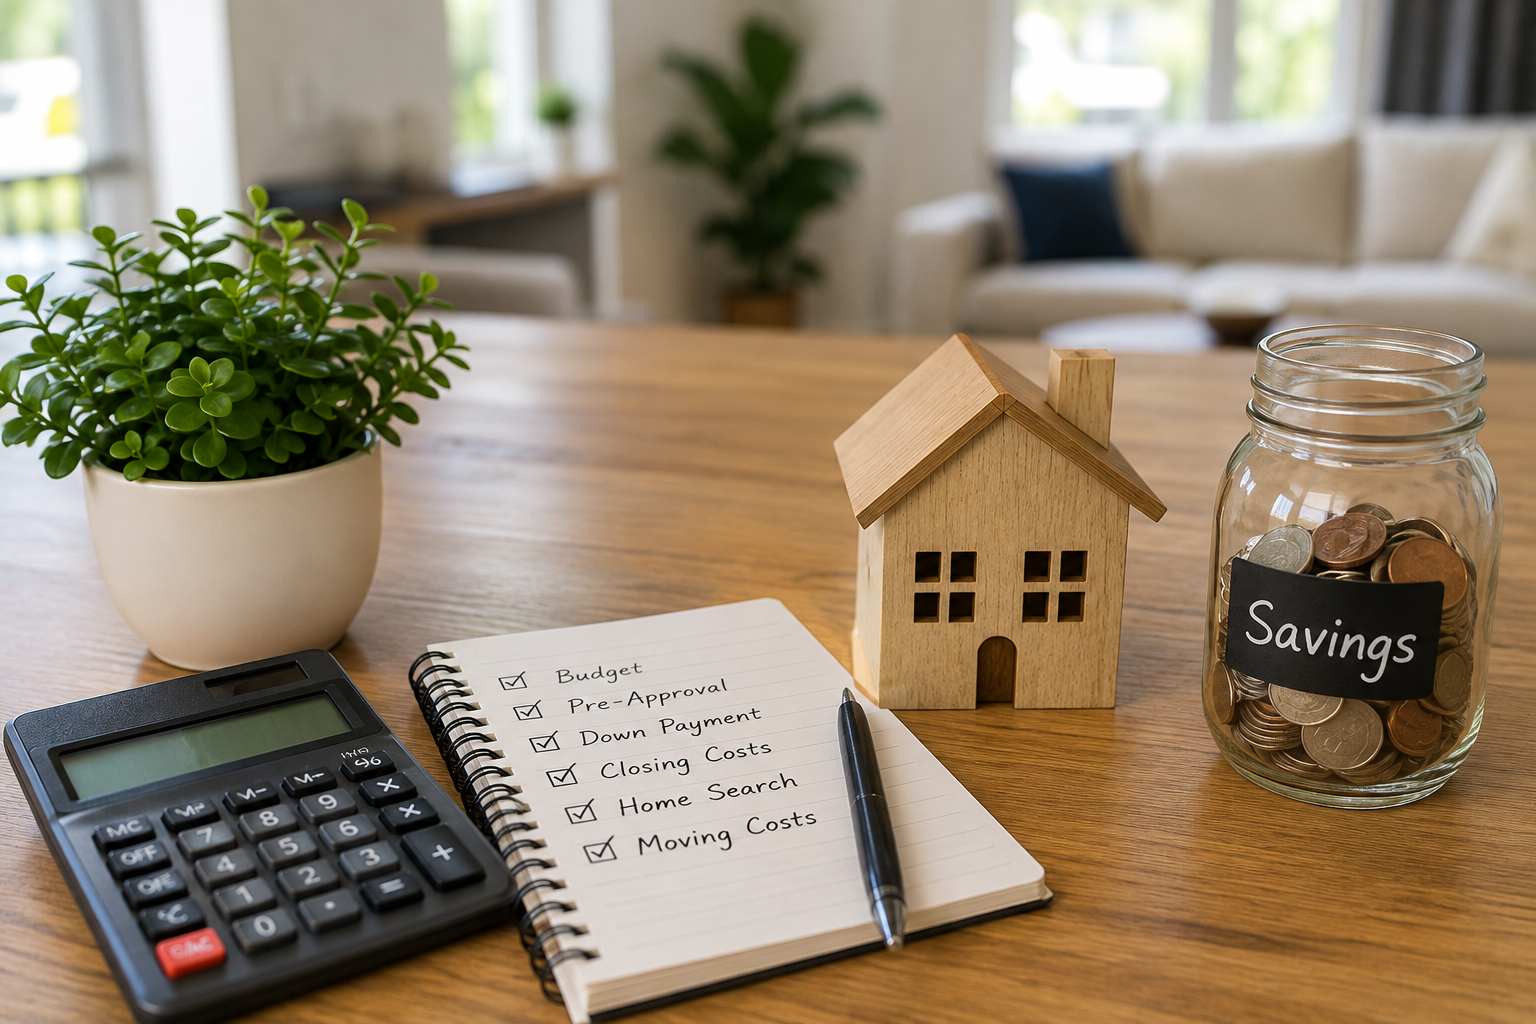
Good question. Because your down payment is not the only money involved in buying a home.
But that also doesn't mean you need some enormous pile of cash sitting around before you can become a homeowner.
Let's break it down.
Your Down Payment Is Only One Piece
Your down payment is the portion of the purchase price you're paying upfront instead of financing.
And despite what people still tell me all the time, 20% down is not a requirement for every buyer.
Depending on your loan program and qualifications, there may be options requiring considerably less.
That's a conversation I want you having with a lender early—not after you've already decided homeownership is out of reach.
Then There's Your Earnest Money Deposit
Once a seller accepts your offer, you'll typically make an earnest money deposit.
Think of it as money you're putting forward to show that you're serious about purchasing the home.
Here's the part buyers sometimes miss:
Your earnest money isn't just an additional fee that disappears.
Assuming the transaction closes, it's generally credited toward the money you're already responsible for bringing into the transaction.
So when we're planning your purchase, I want you to understand where your money is going, not just hear a bunch of dollar amounts thrown at you.
Don't Forget Closing Costs
This is the category that surprises a lot of first-time buyers.
Closing costs can include things like lender fees, appraisal, escrow and title charges, prepaid property taxes, homeowners insurance and other costs associated with completing the transaction.
The exact amount depends on your loan, purchase price and transaction.
And depending on the property and the market, we may also be able to negotiate for the seller to contribute toward certain allowable buyer costs.
Notice I said may.
I don't want you building your entire homebuying plan around money we haven't negotiated yet.
And Please Don't Empty Your Bank Account
This one matters to me.
Just because you technically can bring every dollar you have to closing doesn't mean you should.
You're going to own a house after this.
Things happen.
You may need to move.
You may want furniture.
Something may break.
Life will continue to life.
I want to know what you're comfortable spending and what you want left in reserves after you get the keys.
That's a very different conversation from simply asking, “What's the maximum house I qualify for?”
So How Much Do YOU Need?
That's the part I can't answer with one generic number in a blog.
Your answer depends on:
- Your purchase price
- Your loan program
- Your down payment
- Your estimated closing costs
- Any assistance programs you qualify for
- Any credits we're able to negotiate
- How much money you personally want left after closing
This is exactly why I teach buyers to understand the process before they start falling in love with houses online.
You don't need to know everything yet.
You just need to know your numbers.
If you're thinking about buying in Southern California and want to understand how the entire process works before you're ready to make a move, join our free home buying class.
Register for the FREE SoCal Home Buying Class
Mercedes Erhahon – RESWealthy Team
Real Brokerage, Powered by PLACE
909-413-0602
www.RESWealthyTeam.com
Brian Erhahon
| Brian & Mercedes Erhahon, RESWealthy Team | REAL | PLACE
or another way