Categories
Buying & Selling, Market Updates, Real Estate TipsPublished August 17, 2026
The Buyer Asked for a Credit. Should I Say No?
The Buyer Asked for a Credit. Should I Say No?
You finally get an offer on your home.
You look at the price.
Okay...
Then you keep reading.
The buyer wants a credit.
And immediately you think:
“Absolutely not. I already agreed to sell the house. Now they want me to pay their costs too?”
I understand why sellers react that way.
But before we answer, I want to look at the whole offer.
A Credit Is One Piece of the Deal
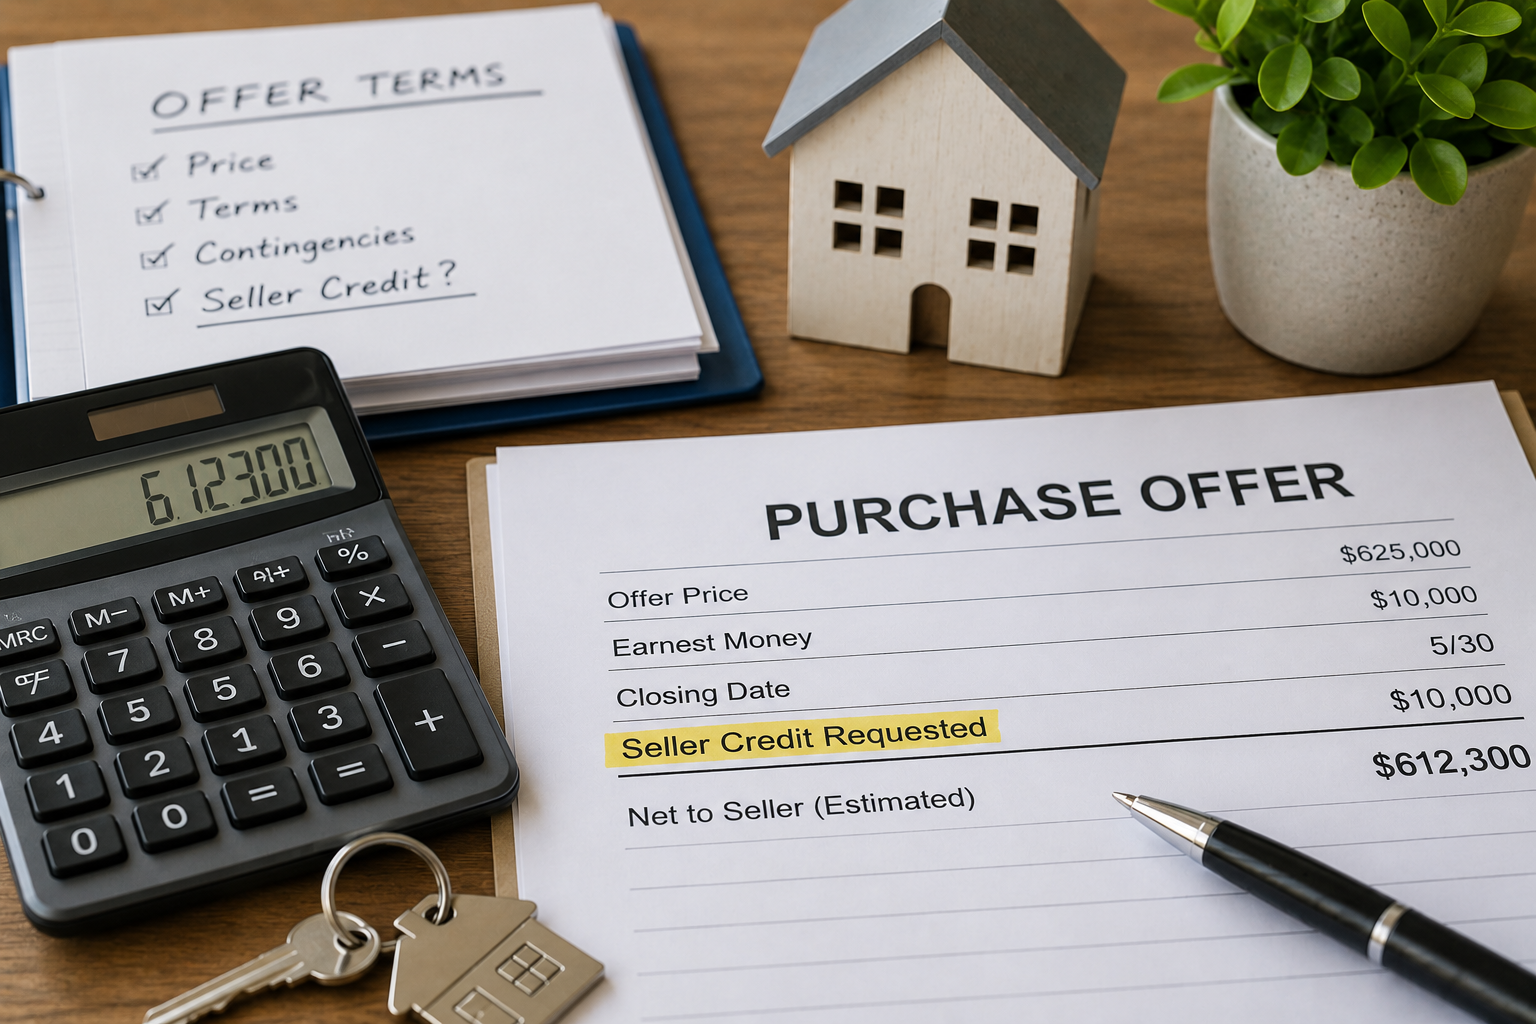
An offer isn't just the purchase price.
There's financing.
Closing timeline.
Contingencies.
Requested credits.
Repairs.
Possession.
And ultimately, your estimated net proceeds.
That's why I don't like evaluating an offer one line at a time.
A buyer asking for a credit doesn't automatically make it a bad offer.
And a buyer offering full price doesn't automatically make it a great one.
We have to see how everything works together.
Why Are Buyers Asking?
Affordability is a major factor in today's market, and seller credits have become part of the conversation in many transactions.
That doesn't mean you have to give one.
Buyers may be trying to reduce the amount of cash they need at closing, address repairs, or structure their financing differently.
The better question isn't:
“Why should I pay their costs?”
It's:
“What does this request mean for my bottom line, and what are we getting in return?”
That's the conversation I want to have with my seller.
Look at Your Net
Let's say one buyer offers a higher price but asks for a credit.
Another buyer offers less and asks for nothing.
Which one is better?
You can't answer that from the purchase price alone.
I want an estimated net sheet in front of us so we can compare what you're actually walking away with.
Then we consider the rest of the terms.
Maybe the offer with the credit nets you more.
Maybe it doesn't.
But now we're making a decision based on the actual numbers, not reacting to one line in the offer.
You Can Negotiate the Credit Too
A buyer asking for $10,000 doesn't mean your choices are:
Accept $10,000 or reject the entire offer.
It's a negotiation.
Depending on the situation, we may accept it, decline it, reduce it, adjust another term, or counter the offer in a completely different way.
And this is where having someone representing your interests matters.
If we're being asked to give something, I want to understand why, whether it makes sense, and what leverage we have in return.
Just because something is requested doesn't mean my seller automatically gives it.
My Advice
When you receive an offer, don't get stuck on one number.
Ask:
What am I actually netting?
How strong is this buyer?
What are they asking me to give up?
What can we negotiate in return?
And how does this offer compare to the activity we've been seeing?
A buyer asking for a credit doesn't mean we're simply going to give it to them.
My job is to look at the entire offer, understand where we have leverage, and negotiate from a position that protects your bottom line and your best interests.
Sometimes that means pushing back on the credit.
Sometimes it means agreeing to part of it while strengthening another term.
And sometimes the strongest response is simply no.
Every dollar and every term matters. My job is to know where we have leverage, use it, and negotiate the strongest deal possible for my seller.
Mercedes Erhahon – RESWealthy Team
Real Brokerage, Powered by PLACE
909-413-0602
www.RESWealthyTeam.com
Brian Erhahon
| Brian & Mercedes Erhahon, RESWealthy Team | REAL | PLACE
or another way